
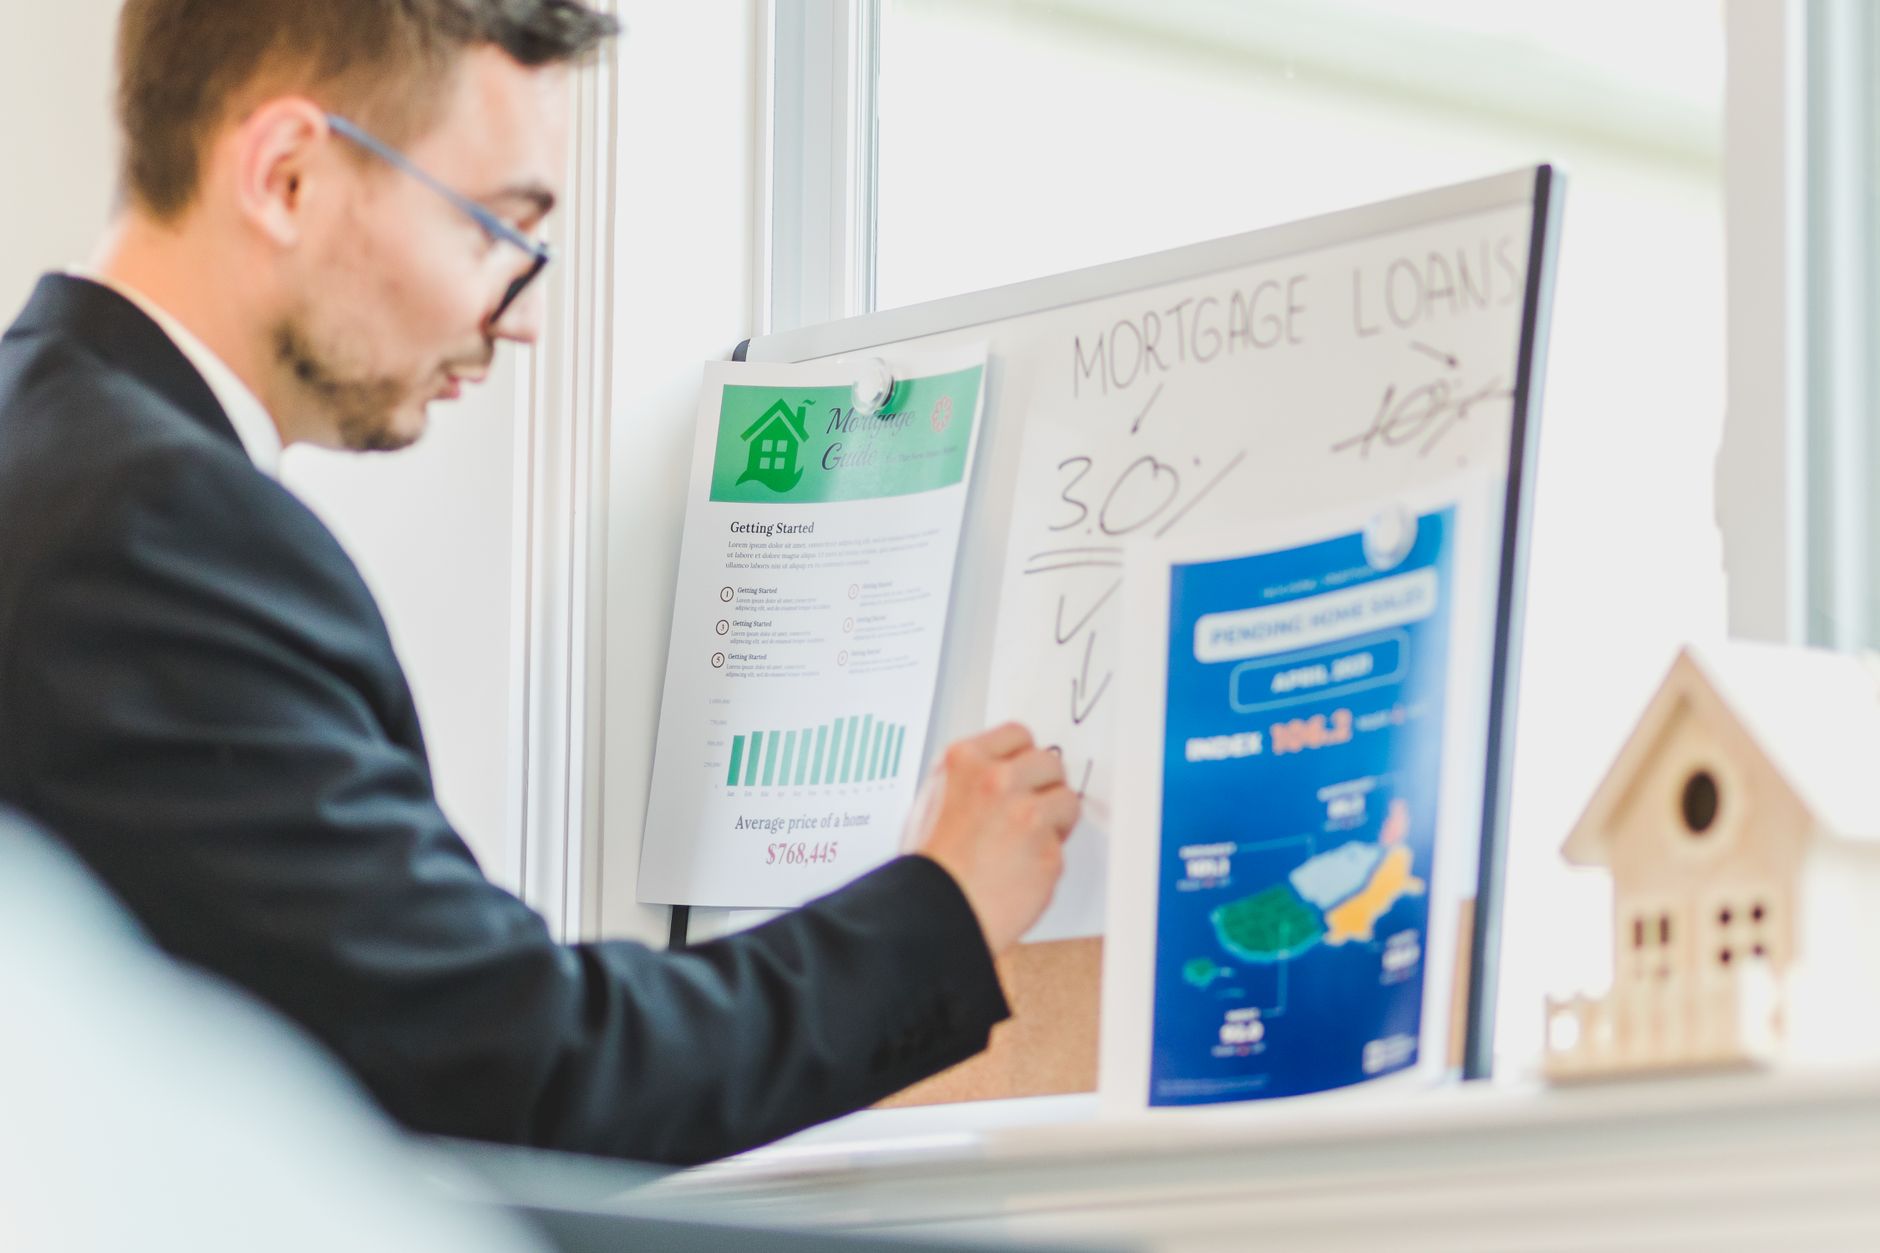
Riskier mortgages are gaining popularity among borrowers, with nearly 10% opting for them last week as rates soared over 7%. This trend raises concerns about financial stability and long-term implications for homeowners.
What Are Riskier Mortgages?
In recent weeks, there has been a notable increase in the popularity of riskier mortgages, with nearly 10% of borrowers opting for these unconventional loan types. As interest rates soar over 7%, many homeowners are seeking alternative financing options to secure their dream homes. But what exactly are riskier mortgages?
Riskier mortgages typically include features that can present significant challenges to borrowers, such as:
- Adjustable-rate mortgages (ARMs): These loans start with a lower fixed interest rate that eventually adjusts to market rates, potentially leading to higher monthly payments.
- Interest-only loans: Borrowers pay only the interest for a set period, which can result in large lump-sum payments later.
- Negative amortization loans: Payments may not cover the interest owed, causing the loan balance to increase over time.
While these options may provide immediate relief for some, they carry inherent risks that could lead to financial instability if not managed carefully. As borrowers navigate this changing landscape, it is crucial to weigh the potential benefits against the long-term implications of taking on such debt.
Understanding the Current Market
The current mortgage market is experiencing significant shifts as interest rates continue to rise. With rates soaring over 7%, many borrowers are feeling the pressure to secure financing before conditions worsen. In this environment, nearly 10% of borrowers have opted for riskier mortgages, a trend that could have serious implications for both individuals and the broader economy.
Understanding the dynamics at play is crucial for potential homebuyers. As traditional fixed-rate mortgages become less affordable, many are turning to alternatives that offer lower initial payments but come with higher long-term risks. These options may include:
- Adjustable-rate mortgages (ARMs) – Loans where the interest rate changes after an initial fixed period.
- Interest-only loans – Borrowers pay only the interest for a set period, deferring principal payments.
- Balloon mortgages – Loans that require a large payment at the end of the term.
While these riskier mortgages may provide a short-term solution, they can lead to financial instability if rates rise further or if borrowers face income disruptions.
Impact of Rising Interest Rates
The recent surge in interest rates has significantly influenced borrower behavior, prompting an alarming trend towards riskier mortgages. As rates climbed above 7%, nearly 10% of borrowers chose these high-risk options, reflecting a growing willingness to engage in potentially perilous financial decisions.
Homebuyers are increasingly drawn to adjustable-rate and interest-only mortgages, attracted by lower initial payments. However, this can lead to substantial financial strain when rates adjust or when principal payments come due. The implications of this trend are concerning, as many homeowners may find themselves unprepared for the financial burden that follows.
Moreover, the rise in riskier mortgages raises questions about the long-term stability of the housing market. Experts warn that if interest rates continue to rise, many borrowers may face difficulties in maintaining their mortgage payments, leading to a higher risk of defaults. The potential for a wave of foreclosures looms large, reminiscent of the financial crises experienced in the past.
As the landscape shifts, both borrowers and lenders must navigate these turbulent waters with caution to mitigate risks associated with this growing trend.
Why Borrowers Are Choosing Riskier Options
In the face of rising interest rates, many borrowers are turning to riskier mortgages as a means of securing financing for their homes. This trend is particularly concerning given that nearly 10% of borrowers opted for these options last week, as rates soared over 7%. Several factors contribute to this growing preference for riskier mortgages.
- Affordability Challenges: With traditional mortgage rates climbing, many prospective homeowners find themselves priced out of the market. Riskier mortgages often come with lower initial payments, making them more attractive to those struggling to afford a home.
- Short-Term Solutions: Some borrowers view riskier options as a short-term solution, believing they can refinance when rates stabilize or drop. This gamble, however, poses significant financial risks.
- Increased Competition: As more buyers enter the market, competition intensifies, pushing some to take on riskier mortgages to close deals quickly.
While these strategies may provide immediate relief, they could lead to severe financial consequences in the long run, especially if interest rates continue to rise or economic conditions worsen.
Advice for Homebuyers
As the trend of riskier mortgages continues to rise, potential homebuyers are urged to approach the market with caution. Experts emphasize the importance of thoroughly understanding the implications of choosing a less conventional loan. Here are some key pieces of advice:
- Assess Your Financial Situation: Before considering any mortgage, evaluate your current financial health, including income stability, savings, and existing debt. This assessment will help determine the level of risk you can afford.
- Research Mortgage Options: Take the time to compare different types of mortgages. While riskier mortgages may seem appealing due to lower initial payments, they can lead to significant financial strain in the long run.
- Consult a Financial Advisor: Engaging with a financial expert can provide valuable insights tailored to your situation. They can guide you through the complexities and help you make informed decisions.
- Consider Long-Term Implications: Understand that opting for riskier mortgages may result in higher payments and potential foreclosure risks if market conditions shift.
Making informed choices is crucial for navigating this challenging housing market.
Long-Term Risks of Riskier Mortgages
The surge in popularity of riskier mortgages raises significant concerns about long-term financial stability for borrowers. While these options may provide immediate relief or help secure a home in a competitive market, they often come with hidden dangers that can lead to severe repercussions down the line.
Borrowers who choose riskier mortgages may find themselves vulnerable to fluctuating interest rates and potential increases in monthly payments that could strain their budgets. Many of these loans involve adjustable-rate mortgages (ARMs), which can start with lower payments but escalate over time, creating uncertainty for homeowners.
In addition, the lack of rigorous underwriting standards for some of these products can lead to borrowers taking on more debt than they can realistically manage. This situation is particularly perilous in a volatile economic environment, where job security may wane and home values can decline.
Furthermore, as the market evolves, the potential for refinancing options could diminish, leaving borrowers trapped in unfavorable loans. Homebuyers are advised to carefully consider the implications of opting for riskier mortgages and to consult with financial professionals before making decisions.
Expert Opinions on Mortgage Trends
As the mortgage landscape continues to evolve, experts are increasingly concerned about the rise of riskier mortgages. With nearly 10% of borrowers opting for these loans last week alone, many analysts warn that this trend could lead to significant financial strain for homeowners.
According to Dr. Emily Carter, a housing market analyst, “The allure of lower initial payments is driving borrowers toward riskier options, but they must consider the long-term implications.” She emphasizes that while these mortgages may provide short-term relief, the potential for payment shocks could be detrimental as rates increase.
Furthermore, John Smith, a financial advisor, highlights the importance of financial literacy in this environment. “Borrowers should fully understand the risks associated with adjustable-rate mortgages and other non-traditional options. It’s crucial to weigh the benefits against the potential for future financial instability.”
Experts also note that the current economic climate, characterized by soaring interest rates, exacerbates these risks. As competition for homes intensifies, and affordability becomes a pressing issue, the shift toward riskier mortgages may continue to rise, posing challenges for both borrowers and lenders alike.
Future Outlook for Borrowers
As the landscape of home financing continues to evolve, the future outlook for borrowers considering riskier mortgages remains uncertain. With nearly 10% of borrowers opting for these loans last week amid soaring interest rates exceeding 7%, many are weighing the immediate benefits against potential long-term consequences.
Experts suggest that while the allure of lower initial payments may be tempting, the volatility associated with riskier mortgages could lead to financial strain as rates fluctuate. Borrowers may find themselves in precarious situations if economic conditions shift, resulting in payment increases that exceed their budget.
In light of recent trends, it is crucial for potential homebuyers to conduct thorough research and consider their financial stability before committing to riskier options. To better prepare for future challenges, borrowers should:
- Evaluate their long-term financial goals.
- Consult with financial advisors about the implications of their mortgage choices.
- Keep abreast of market trends to anticipate potential changes in interest rates.
Ultimately, making informed decisions today can safeguard borrowers’ financial futures as they navigate the complexities of the housing market.
Photo by RDNE Stock project on Pexels

Leave a Reply